
The Financial Markets Authority – Te Mana Tātai
Hokohoko (FMA) has reviewed how fees, incentives and
commissions are disclosed across managed investment schemes,
discretionary investment management services (DIMS), and
financial advice providers. While disclosure was generally
satisfactory, the review found some issues with clarity,
completeness and consistency while also highlighting good
practice, including clear upfront fee summaries and simple
explanations of tiered fees.
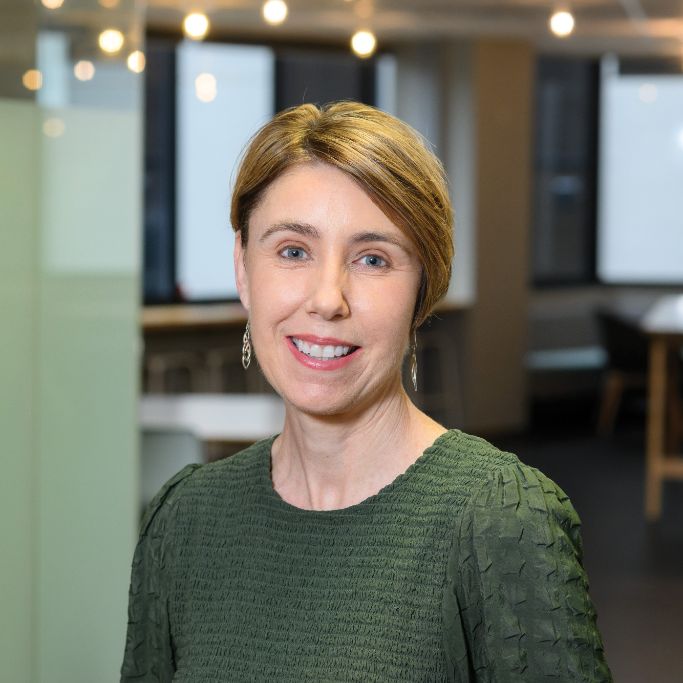
Unger, FMA’s Executive Director for Response and
Enforcement (Photo/Supplied)
“Fees
affect what investors and consumers get back from a
financial product,” says the FMA’s Executive Director
for Response and Enforcement, Louise Unger. “Clear
disclosure lets people see the overall cost of a product or
service, compare their options, and decide whether something
suits them. The review looked at whether investor-facing
disclosure lets people do that.”
The schemes
reviewed were run by 37 managers. The review also covered a
range of DIMS providers and a selection of financial advice
providers. The FMA assessed disclosure against the Financial
Markets Conduct Regulations 2014 and its own
guidance.
“Most problems the FMA found were minor,
but they contributed to making costs harder to
understand,” says Unger. “Fee information was sometimes
spread across several documents without clear signposting.
In some instances, different documents used different words
for the same charge. Some disclosure explained what a fee
was called but did not clearly explain how it worked or how
it affected returns.
Advertisement – scroll to continue reading
“Investors should be able to
see what they are paying and understand how it affects their
money, without hunting through several documents to get the
full picture. Most providers are doing a reasonable job, and
where we saw weaknesses, they were about clarity and
consistency, not anything hidden. Managing conflicts from
the way financial service providers are paid is one of our
priorities this year, and clear fee disclosure is part of
that.”
Around a third of the 55 managed investment
schemes reviewed used the key information summary to set out
fees plainly up front, then pointed investors to the detail.
Some DIMS providers showed tiered fees in a simple table and
explained how charges shifted as the amount invested
grew.
The FMA has given feedback to providers and
statutory supervisors where it found issues. Some have
already updated their disclosure, and the FMA will carry out
targeted follow-up reviews to check the rest have
acted.
“In short, providers should explain material
fees in plain language, say when payments apply, and keep
the information consistent across every document,” says
Unger.
The report sets out practical recommendations
to help providers deliver clear, concise and effective
disclosure of fees, incentives and commissions, making it
easier for investors and consumers to understand the costs
of financial products and
services.
Notes
- The review document can
be downloaded here
(https://www.fma.govt.nz/library/reports-and-papers/fees-incentives-and-commissions-disclosure-review/) - The
review covered 55 managed investment schemes run by 37
managers, along with a selection of DIMS providers and
financial advice providers. - Managing conflicts from
remuneration structures is a regulatory priority for the FMA
in the 2026/27 financial year.
About the
FMA
The Financial Markets Authority – Te Mana
Tātai Hokohoko (FMA) is the New Zealand government agency
responsible for financial markets regulation. Our purpose is
to promote and facilitate the development of fair, efficient
and transparent financial markets. For more information
visit fma.govt.nz.